Business Funding Options for Startups: A Comprehensive Guide
Key Takeaways
- Startup funding mostly breaks down into five buckets — loans, equity financing, grants, crowdfunding, and angel investment — and each one comes with its own strings attached.
- Outside money buys you more than cash. It buys you room to hire, market, and grow faster than revenue alone would let you.
- Lenders and investors respond to preparation. A tight business plan, decent credit, and a network you've actually built count for more than most founders expect.
- No funding yet? That's not the end of the road. Personal savings, help from family, or plain old bootstrapping have launched plenty of companies you'd never guess started that way.
- Every dollar you bring in costs something — interest, equity, or collateral — so read the fine print before you sign anything.
Business Funding Options for Startups: A Comprehensive Guide
If you're building a startup, you've probably already run into the wall every founder hits eventually: there are a dozen ways to get money into your business, and almost no clear sense of which one actually fits yours. Banks want collateral. Investors want equity. Grants want paperwork you didn't even know existed. Here's an honest look at the real options — loans, equity financing, grants, crowdfunding, and angel investors — so you can figure out what actually makes sense for where your business is right now.
Types and Sources of Business Funding
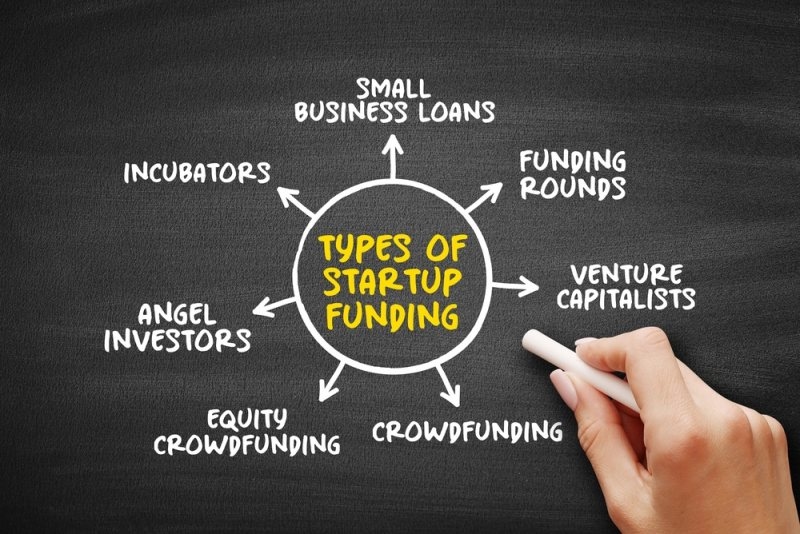
Loans, equity, grants, crowdfunding, angel money — these aren't interchangeable. The right pick usually comes down to how fast you need the cash and how much control you're okay handing over.
1. Loans
Probably the first thing that comes to mind. Banks, credit unions, and other traditional lenders will hand you a lump sum, but they want collateral and a credit check first, and how much you can borrow usually tracks pretty closely with your credit score and income. Straightforward, sure. Forgiving if things go sideways? Not really.
2. Equity Financing and Venture Capitalists
This one's different — you're not borrowing, you're selling a slice of your company for capital, usually to cover operations or fund growth. Venture capitalists work the same way. They're chasing businesses with real upside, and they'll bet on you in exchange for a piece of the pie.
3. Grants
About as close to free money as startup funding gets. Government agencies and private organizations hand out funds you never have to pay back. The catch, and there's always a catch, is that qualifying usually means clearing a pretty strict set of criteria. Don't expect a fast yes.
4. Crowdfunding
Flip the model on its head: instead of one lender or investor, you're asking a crowd of people to chip in small amounts. Works well for launches, new products, or just keeping the lights on while you get going.
5. Angel Investors
Individuals, often with money to spare and a good eye for early-stage businesses, who invest their own cash for equity. They tend to move faster than institutional investors, and a lot of the time they bring more to the table than just a check.
Must Read: Different Stages of the Branding Process that Businesses Use
Why Bother With Outside Funding at All?
Fair question. For most startups, the honest answer is: eventually, yes, because bootstrapping alone only gets you so far.
1. Access to Capital
The obvious one. Real capital means buying equipment, bringing on employees, and putting actual money behind marketing instead of hoping word of mouth carries the whole thing.
2. Healthier Cash Flow
Funding smooths out the bumps. It covers operating costs, restocks inventory, and makes payroll during the slow stretches every business runs into sooner or later.
3. Room to Grow
With capital behind you, expansion and new markets stop being someday plans and start being actual goals — and with financing conditions still shifting into 2026, that extra cushion matters more than it used to.
How to Actually Land Funding?
Getting funded rarely comes down to luck. It comes down to showing up prepared and doing the unglamorous groundwork most founders would rather skip.
1. Know Your Options First
Before you approach anyone, get clear on which funding types actually fit your business. Much easier to pitch when you're not still figuring out what you're pitching for.
2. Put a Real Business Plan Together
Strategy, projections, growth targets — all of it. This isn't a box to check. It's often the single biggest factor in whether a lender or investor takes you seriously at all.
3. Get Your Credit in Order
If a loan's on the table, your credit score is coming with you into every conversation. Pay bills on time now, clean up your history now, thank yourself later.
4. Get Out There and Network
A lot of funding still happens through people, not cold applications. Show up to events, talk to other founders, stay visible to the people who might one day write you a check.
5. Don't Quit After the First No
Rejection is part of it, not a sign you're doing something wrong. Keep refining the pitch, keep reaching out. Persistence closes more deals than most people expect.
When Traditional Funding Isn't an Option?
Not every founder qualifies for a loan or lands an investor on the first try, and that's genuinely fine. There's more than one way to get a business off the ground.
1. Your Own Savings
Not glamorous, but direct, fast, and free of strings. Plenty of founders have used their own savings to get their business off the ground long before they ever approached a lender.
2. Friends and Family
People who already believe in you are sometimes your fastest source of cash. Just put the terms in writing — informal money among family has a way of turning complicated once expectations aren't spelled out up front.
3. Bootstrapping
Funding the business yourself: savings, credit cards, revenue you reinvest instead of pocket. Slower, no argument there. But you don't answer to anyone but yourself.
Grants Worth Looking Into
Grants get their own spotlight here because they're the rare funding option that doesn't need to be paid back — assuming you can clear the bar to qualify.
1. Small Business Administration
The SBA runs a range of grant programs aimed at helping startups fund operations and expansion. Usually the first stop worth checking.
2. State and Local Grants
Don't overlook what's sitting closer to home. Plenty of states and municipalities run their own grant programs to support local business growth.
3. Crowdfunding as a Grant Alternative
If formal grants don't work out, crowdfunding's worth a second look here too. It's a flexible way to raise money for operations, growth, or a launch without giving up equity or taking on debt.
Top Pick: What are the Top 7 AI Marketing Tools for Customer Engagement?
Weighing the Trade-Offs
No funding option comes free of downsides. Knowing what you're signing up for, good and bad, makes the decision a lot less stressful down the line.
1. What You Gain
Capital for equipment, hiring, and marketing. Steadier cash flow through the slow stretches. Runway to expand into new markets when the timing's actually right.
2. What It Costs You
Most funding comes with debt attached, and debt is a risk no matter how you slice it. Interest adds up, often more than people expect going in. And collateral requirements — a personal guarantee, a lien on assets — mean you need to understand the terms fully before you sign, not after.
Conclusion
To pick the best route, spend real time learning. Make a business plan that is easy to follow and filled with real details. Check your credit and try to improve it before you ask for money. Also, speak with people who have invested before. In practice, who you know can matter as much as what you have. If you handle these steps, you are more likely to secure the funds you need to grow.
Frequently Asked Questions
What is the best type of business funding for a new startup?
Depends on where you're standing. Solid credit and steady revenue projections? A loan might make the most sense. Want to skip debt entirely and don't mind giving up some ownership? Angel investors or venture capital could be the better fit. And it's always worth checking grants and crowdfunding first, since neither one requires repayment.
How much funding do I actually need to start a business?
Start with the real costs — equipment, licensing, initial inventory — then tack on three to six months of operating expenses at minimum. A detailed business plan with actual financial projections gets you to a real number a lot faster than guesswork ever will.
Do I need good credit to get business funding?
For a traditional loan, pretty much, yes. Lenders are going to look at your credit score, your income, and what you can put up as collateral. If your credit isn't there yet, grants, crowdfunding, help from friends and family, or bootstrapping can carry you while you build it up.
Are grants really free money for startups?
They don't need to be repaid, which is the appealing part, but "free" is a stretch. Between the strict eligibility rules, the competition for each one, and the reporting once you're awarded, getting a grant is its own kind of work.
What's the difference between equity financing and a business loan?
A loan is money you borrow and pay back with interest, and you keep full ownership the whole way through. Equity financing means trading a piece of your company for capital — you're not repaying it directly, but you're giving up some control and a share of future profits.
Can I combine multiple funding options for my startup?
Definitely, and a lot of founders end up doing exactly that. Bootstrap the early costs, bring in a small round from friends and family, then move on to a loan or an angel investor once the business has some real traction. Just make sure anything involving other people's money gets put in writing, so nobody's left guessing later.
This content was created by AI